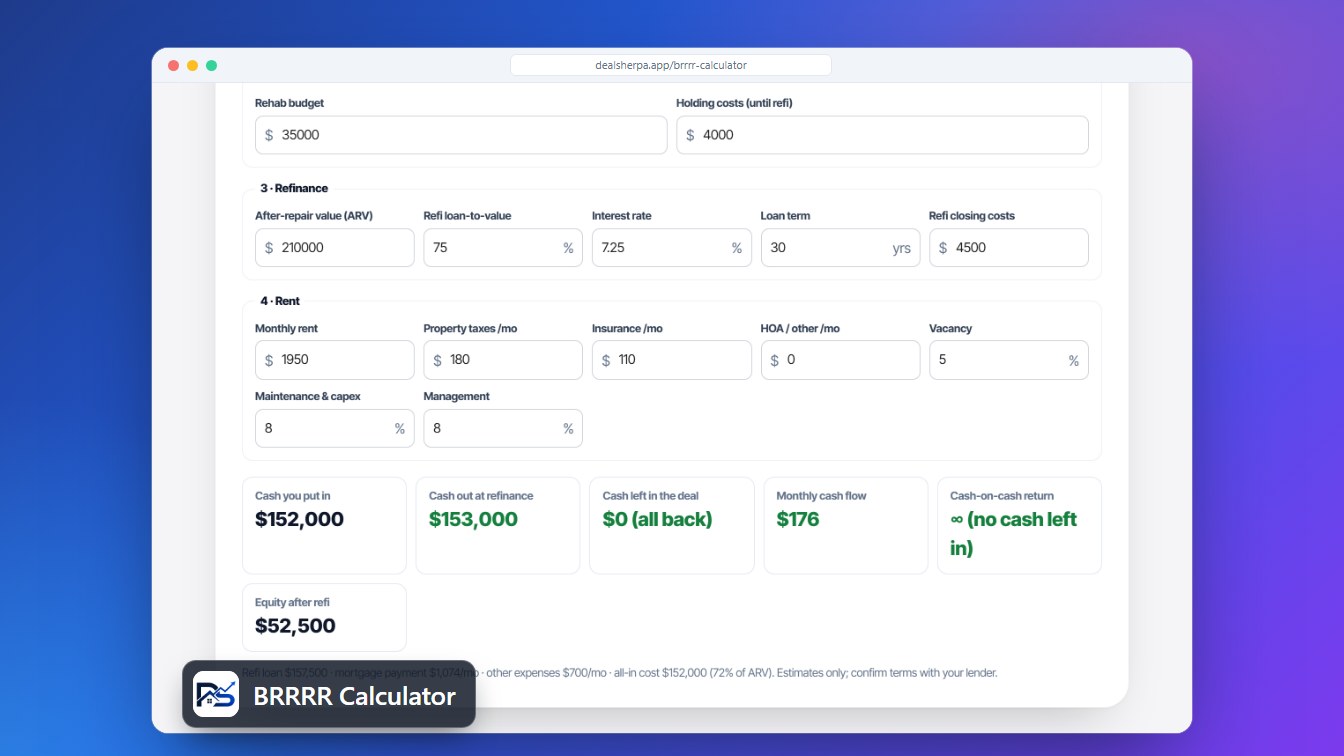
BRRRR (Buy, Rehab, Rent, Refinance, Repeat) had a golden era from 2019 to 2022. Then rates doubled and everyone declared it dead. Is it?
The honest answer: it depends on your entry point.
With a 7–8% refinance rate, the numbers only work if you buy right. That means acquisition at or below your MAO and a rehab that maximizes rent per dollar spent. The days of buying at 80% of ARV and refinancing at par are over — you need to be at 65–70% to make the refi work without bringing money back to the table.
Where the math still works
Rent-to-price ratios are what make or break BRRRR, and they're far better in many Midwest and Southern metros than on the coasts. Say a $180K acquisition on a 3/1 rents for $1,600–$1,800. A $220K rehabbed value produces a 1% rule property — which, while not the benchmark it once was, still produces positive cash flow at 7.5% after a 75% LTV cash-out refi.
The deals that work
Focus on properties where:
- You can acquire below $170K
- Rehab is under $35K (cosmetic + systems, not gut)
- Projected rent is $1,500+
- ARV supports a 75% LTV refi above your all-in cost
That combination exists in plenty of working-class neighborhoods in affordable metros. It's not everywhere, but it's there.
The deals that don't work
Anything that requires a full gut rehab in today's contractor market will struggle to pencil. If your rehab budget is $60K+, run the flip scenario instead.
Deal Sherpa's BRRRR calculator shows you the cash-on-cash and refi waterfall on every listing in real time.
 DealSherpa Team